The Consumer Financial Protection Bureau may reduce regulation for some companies in the international money transfer market because it’s “concerned” about whether the cost burdens outweigh the benefits.
The federal agency said this month that it’s mulling a change to its definition of a “larger” participant in that market, thereby changing which ones are subject to its supervision. In the Aug. 8 Federal Register post, the bureau said it’s concerned about its current definition, issued in 2014, because it may result in overly burdensome costs and unneeded regulatory oversight.
Currently, the larger participant definition includes all nonbank entities making one million in international transfers annually. The agency acknowledged it hasn’t been able to source precise data on the market.
Nonetheless, the bureau said it intends to “propose amending the test to define larger participants in the international money transfer market.”
Major international money transfer companies include long-standing stalwarts Western Union and MoneyGram, but younger fintechs, such as Remitly and Euronet, have increasingly entered the field too.
“The Bureau is concerned that the benefits of the current threshold may not justify the compliance burdens for many of the entities that are currently considered larger participants in this market, and that the current threshold may be diverting limited Bureau resources to determine whom among the universe of providers may be subject to the Bureau’s supervisory authority and whether these providers should be examined in a particular year,” the agency said in its post.
The proposed change comes as President Donald Trump seeks to put his stamp on the payments system, largely by reversing the Biden administration CFPB regulation that had been aimed at emerging services such as buy now, pay later and earned wage access.
The agency’s mission has been squelched as the Trump administration pursues the firing of about 95% of the bureau’s staff.
In other moves affecting payments, Trump issued an executive order in March seeking to “modernize” the U.S. payments system, partly by banishing the federal government’s use of paper checks.
In its post, the CFPB said its concerns included that the benefits of the supervision may not outweigh the costs of compliance for the covered entities or the agency; that the current definition may disproportionately impact smaller market players; and that covering so many entities may divert scarce bureau resources.
The agency also observed that the industry is highly concentrated, so it postulated that it could narrow the definition of a large market participant and still capture those entities that handle the bulk of the transactions.
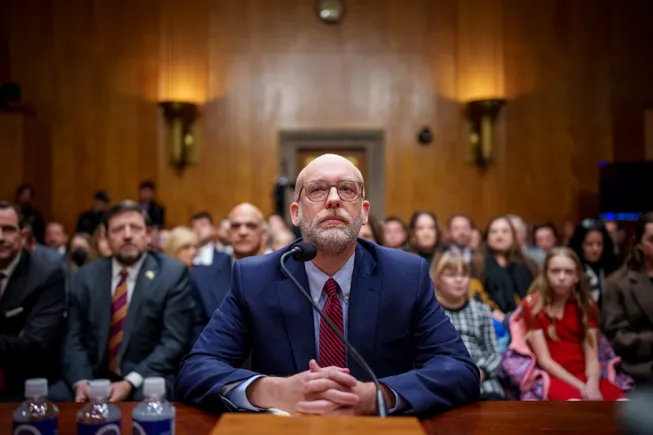
“This concentration supports the fact that a higher threshold might better balance the goals of protecting consumers while also not unnecessarily imposing costs on covered persons,” the CFPB said in the notice signed by Acting Director Russell Vought.
Specifically, the bureau observed that the current definition, based on one million yearly transactions, results in oversight of 28 nonbank providers managing 98% of transfers. By contrast, raising the threshold to 10 million in annual transactions would result in oversight of 15 providers handling 94% of transfers, while raising the bar to 30 million would mean oversight of eight firms covering 77% of the market, and raising it to 50 million would regulate four participants with 61% of the market.
“The current threshold is probably overinclusive,” said Holland & Knight attorney Eamonn Moran specializing in financial services. Moran suggested the agency moving to increase the threshold would better focus regulation on the largest players. He also noted that regardless of the definition, the regulations still apply to all the players in the market.
As for consumer protections, there are other aspects of the Electronic Fund Transfer Act that also pertain to remittances, Moran explained. “There are still protections in place,” he said.
Money transfer service providers are essentially the same as those providing remittance services, which enable workers in a foreign country to send money home to family and friends, the agency noted. Such transfers include those sent electronically via apps, or those sent through agents to stores or other outlets, where they can be picked up in the form of cash.
The definition doesn’t distinguish between those sent by people or businesses and isn’t based on the amount of the transfer.
The bureau is also seeking public input on its proposed change, with comments due by Sept. 22. Specifically, the agency asked commenters to provide any information on data for understanding the market; geographic corridors that could be disproportionately affected by a definition change; appropriate criterion for the definition; and costs incurred to comply with regulations.
Only a few comments have been posted so far to the federal docket for such submissions, but they add perspective to the issue.
Kaila Tangney of Denver said that while increasing the threshold for the definition might yield efficiencies for the bureau, it would likely result in more risk and potential disruption for the market, and potentially increased costs.
“Raising the threshold for defining larger participants in the international money transfer market will create long-term implications for businesses by increasing operational risk and reducing regulatory oversight for mid-size and smaller providers,” Tangney said in the Monday comment.
Another commenter, Andrew Gonzalez, contended that if smaller service providers don’t receive as much oversight, it could particularly affect certain communities in Latin America, the Caribbean and Southeast Asia, so he suggested the CFPB assess those risks before any threshold revision. A higher threshold that cuts oversight for smaller entities could also increase fraud and “pricing opacity,” Gonzalez said.
In addition, the reduced regulation for small players might incent big participants to split their entities to skirt oversight, Gonzalez suggested in his comment dated Aug. 8. “This could fragment compliance responsibilities and undermine consumer protections,” Gonzalez wrote. “Alternatively, firms may reduce service in high-risk corridors to avoid compliance scrutiny.”
Alongside the review of the definition of large market participant for the international money transfer market, the federal agency is also considering changing the definitions of big players in three other markets as well, namely car financing, consumer agency reporting and consumer debt collection.
This story is aggregated and curated by Finopulse automated financial research systems for educational and reference purposes. It has been verified for market relevance.