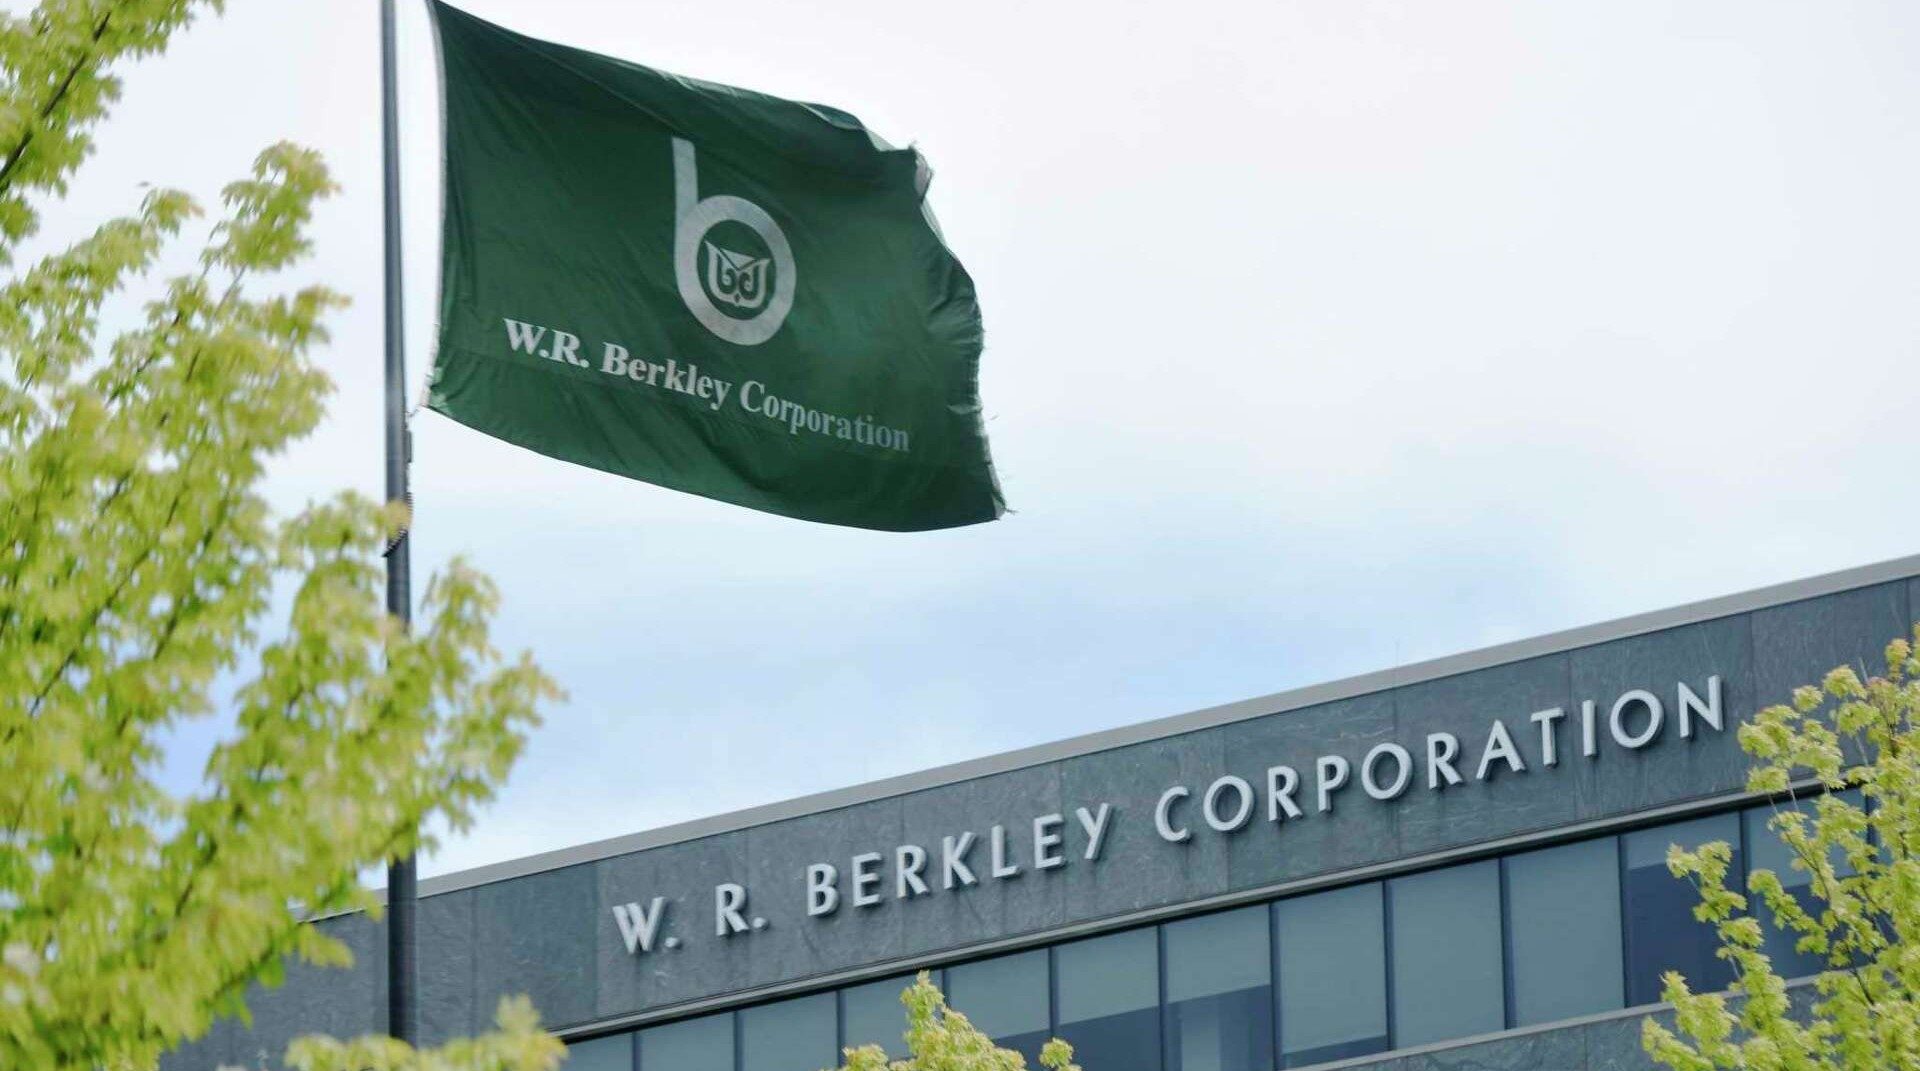
W. R. Berkley Corporation’s reinsurance casualty book shrank 25% in the third quarter compared with a year earlier, the steepest single-quarter drop in a contraction that has now run for three consecutive reporting periods. That retreat, buried in the supplemental data of an otherwise solid set of results, reflects a deliberate pricing judgment that has direct implications for anyone placing specialty casualty business.
Net premiums written in reinsurance casualty fell to $144.2 million in Q3 2026 from $192.7 million in Q3 2025. Over the nine months to September, the line is down 18% year on year.
The reinsurance and monoline excess segment as a whole wrote $368.6 million in net premiums for the quarter, against $417.2 million a year earlier. Insurance segment premiums grew 3.2% over the same period, enough to lift consolidated net premiums written to $3.3 billion and keep the headline combined ratio steady at 90.8%.
Why Berkley is pulling back
The direction has been consistent with what CEO W. Robert Berkley, Jr. has said publicly for several quarters. At the Q4 2025 earnings call in January 2026, he flagged that property catastrophe reinsurance rates had fallen 19% at the January 1 renewals, and that reinsurers missing their property premium targets were leaning into casualty to compensate.
He described early signs of that competitive spillover into casualty as something that had gone “more than we would have anticipated.” By Q2 2026, management described reinsurance conditions as “particularly concerning,” with property eroding rapidly and casualty having never secured the pricing improvement that property had.
The Q3 figures show the pullback continuing. On the earnings call, Berkley was direct about the reason: “What we’re not liking, as we’ve chatted about or commented on for probably not this quarter, maybe years at this stage as it relates to casualty reinsurance are the ceding commissions. We just don’t think it makes economic sense.” He added that the reinsurance segment is likely to keep shrinking at a rate of roughly 10% to 20% for the foreseeable future, and that the company accepts that as a natural consequence of maintaining pricing discipline.
Where Berkley is growing instead
The insurance segment is absorbing the volume. Professional liability net premiums written grew to $322.4 million from $307 million, extending a streak of growth in that line even as the professional liability market broadly softened.
Other liability, Berkley’s largest insurance line at $1.13 billion in Q3 net premiums written, grew 3.8%.
Average rate increases across the insurance segment, excluding workers’ compensation, came in at approximately 4%, a moderation from the 6% to 7% range seen in prior quarters, which aligns with Berkley’s stated shift toward growing volume in lines where it already sees adequate margin rather than pressing for further rate.
A signal embedded in the numbers
The gap between what Berkley is doing in insurance and reinsurance is not incidental. It reflects a view on where the cycle is. Berkley has repeatedly framed its current reinsurance posture as that of a buyer rather than a seller, noting that the property cat treaty renewed with a 19% risk-adjusted rate decrease on their own book. A carrier of Berkley’s scale reducing reinsurance casualty by 25% in a quarter is a pricing signal, rather than a portfolio management footnote. The question for anyone placing reinsurance-backed specialty casualty capacity is whether the carriers still willing to write it are pricing it adequately.
W.
Robert Berkley, Jr. described the quarter as “another excellent quarter” driven by underwriting discipline and investment portfolio performance. Operating income rose 6.4% on a per-share basis to $1.17, and the operating return on equity was 18.8%. Those numbers are accurate. The sharper read is in the segment where business is leaving.
Disclaimer: This story is auto-aggregated by a computer program and has not been created or edited by finopulse.
Publisher: Source link